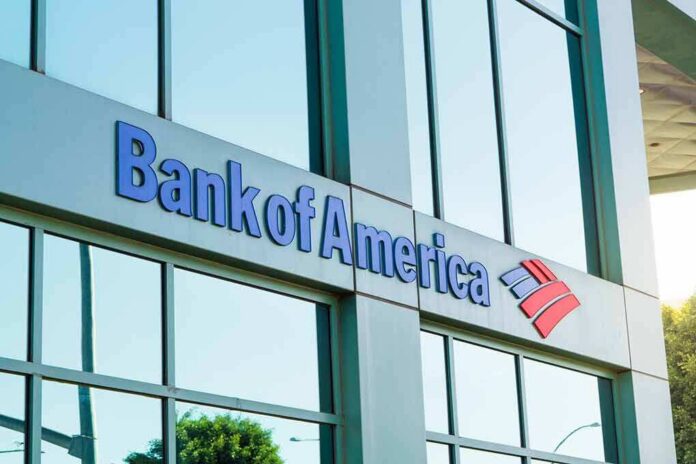
Bank of America failed to promptly report over $5 billion in suspicious transactions, drawing a record $1.2 billion penalty from the Treasury Department.
Story Highlights
- Treasury said Bank of America did not timely report more than $5 billion in suspicious activity
- Over $1 billion involved priority risks, including signs of Chinese laundering networks
- FinCEN issued a $1.2 billion penalty; the bank also faces a $750 million OCC fine
- Bank of America admitted willful Bank Secrecy Act violations in the settlement
What Treasury Found And Why It Matters
The U.S. Treasury Department said Bank of America failed to timely report more than $5 billion in suspicious transactions to the Financial Crimes Enforcement Network (FinCEN). Treasury said more than $1 billion of that activity touched national security and other priority risks, including patterns tied to Chinese money laundering networks and trade-based schemes near the southwest border. These are exactly the blind spots cartels and foreign adversaries try to exploit. When a giant bank misses them, criminals and hostile regimes get a pass they did not earn.
Treasury announced a $1.2 billion FinCEN penalty and highlighted a separate $750 million action by the Office of the Comptroller of the Currency (OCC), underscoring failures across anti-money laundering controls and reporting. CNBC reported the bank admitted it willfully violated the Bank Secrecy Act by failing to keep a compliant program, conduct required checks on foreign correspondent accounts, and file suspicious activity reports. That admission matters. It signals these were not simple paperwork misses but core duty failures to help law enforcement spot crime.
National Security Risks And The China Connection
Treasury’s release said more than $1 billion of the unreported activity implicated national security priorities and included transactions indicative of Chinese money laundering networks. Beijing’s criminal proxies use complex webs to move money and hide its source. When those flows pass unchecked, the damage lands here at home. It can fuel fentanyl, intellectual property theft, or trade fraud hitting American jobs and families. Strong bank reporting is a frontline defense; missed reports open the gate for bad actors.
Regulators point to the bank’s massive scale to show the stakes. CNN reported Bank of America processed more than $9 trillion in transactions in the relevant year, while failing to report over $5 billion in suspicious activity. Even a small failure rate at that scale can mask big harm. That is why federal law demands fast suspicious activity reports. Those reports give agents time to freeze funds, track networks, and stop crimes before they spread.
How The Enforcement Package Fits A Larger Trend
This action fits a longer shift toward tougher anti-money laundering enforcement with big penalties and multiple agencies acting at once. A Congressional Research Service review found a sharp rise in money penalties after 2012, showing regulators use fines to drive compliance change across the system. Large cases like this tell other banks to invest in detection, staffing, and technology. That protects Americans against cartels, cyber thieves, and foreign regimes that try to move dirty money through our financial system.
Bank of America has been hit with $1.21 billion in federal penalties after failing to timely report more than $5 billion in suspicious transactions.
More than $1 billion involved potential national security risks, including activity linked to Chinese money-laundering networks… pic.twitter.com/SJu0Y5SOLr
— Cost of America (@CostOfAmerica) October 14, 2026
Federal action also tells Main Street that the system should follow the same rules we do. Families must follow the law. So must the largest banks. President Trump’s administration has made clear that national security and border-linked crime are top priorities. Stopping suspicious flows linked to Chinese networks and the southwest border aligns with that mission. When banks meet their duties, agents get the leads they need. When banks fall short, criminals get cover.
What Comes Next For Customers And Markets
Customers should expect the bank to strengthen checks on suspicious payments, especially for foreign correspondent accounts and trade finance. That may mean more questions, delays, or account reviews as systems tighten. Some will complain, but stronger controls protect lawful customers by keeping bad actors out. CNBC also reported the bank has said it invested billions in compliance and is far along in its fixes, which is the response regulators expect after problems at this scale.
For markets, the message is simple. Clean up problems fast, or pay a heavy price. The $1.2 billion FinCEN penalty, paired with a $750 million OCC action, signals that agencies will not let weak reporting stand. That is good for honest businesses, veterans starting companies, and families trying to build savings. It keeps the playing field fair by choking off the cash that fuels crime and hostility toward the United States. Strong banks and strong laws work best together.
Sources:
nbcnews.com, home.treasury.gov, cnbc.com, finance.yahoo.com, news18.com, easternherald.com